A personal liquidity coverage ratio is a simple safety score for your money. Banks use this official rule to prove they have enough fast cash to survive thirty days of extreme trouble. When you apply this idea to your home, it shows whether your family can pay all essential bills for one full month if your regular income suddenly stops.
The Missing Household Version
If you search for this term, you will only see complicated laws written for big financial institutions. Governments created strict rules for banks after past financial crises, but nobody created a standard guide for normal families. That can feel confusing, yet you do not need to worry. You can easily borrow this smart banking concept to make your own home feel completely safe and secure. You can protect your peace of mind by checking your cash reserves once or twice every year.
The Formula for a Household
The formula is straightforward. You take your total available cash and safe savings, adjust them for safety, and divide that amount by your living costs during thirty days of hardship. If your final score is one hundred percent or higher, you pass the test. A score of one hundred percent means you have enough resources to cover exactly thirty days of tough times without borrowing money.
Haircuts on Assets
To find your true available money, you must understand a banking word called a haircut. In the financial world, a haircut means reducing the counted value of an investment to protect against sudden price drops.
Cash in your wallet and money in a regular bank account do not get a haircut because one dollar in the bank remains one dollar. In contrast, stocks and mutual funds can swing up and down during a crisis. If you own company stocks, you might apply a twenty percent haircut to them. That means if your shares are worth one thousand dollars today, you count them as only eight hundred dollars in your safety score just to stay cautious.
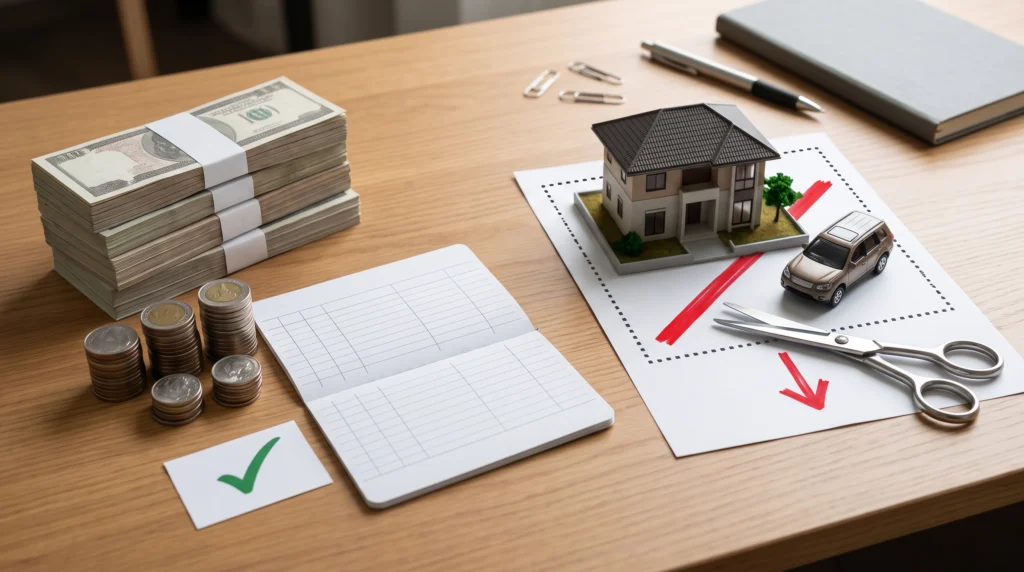
Things like your house, your car, or jewelry are not liquid assets at all. An asset is liquid when you can turn it into usable spending money almost instantly without losing value. Because selling a house takes months, you give physical property a one hundred percent haircut, which means it counts as zero for this thirty day test.
Stress Outflows
The bottom half of the formula measures your stress outflows. A cash outflow simply means money leaving your hands to pay for goods and services.
Under normal conditions, you pay for groceries, rent, entertainment, and gifts. During a severe emergency, such as losing a job or facing a medical problem, you cut unnecessary spending. Your stress outflows include only the bare essentials, such as food, electricity, heating, housing, and basic travel. You also add a small buffer for unexpected surprise bills, such as an urgent home repair.
A Worked Example
Imagine a family with five thousand dollars in a checking account, three thousand dollars in a savings account, and four thousand dollars in standard stock funds. Their checking and savings money suffers no haircut, giving them eight thousand dollars. For their stocks, they take a cautious twenty percent haircut, which turns four thousand dollars into three thousand two hundred dollars. Adding these together gives them eleven thousand two hundred dollars in safe, available assets.
Now look at their costs. In a normal month they spend four thousand dollars, but in a crisis they can cut back to three thousand dollars for basic needs. They also expect a potential emergency car repair of one thousand dollars during that stressful month. That brings their total thirty day stress outflow to four thousand dollars.
When you divide eleven thousand two hundred dollars by four thousand dollars, the answer is two point eight. Multiplying this by one hundred gives a personal liquidity coverage ratio of two hundred and eighty percent. Because this score is far above the one hundred percent mark, this family knows they are safe and can handle severe stress with confidence.
Looking to the Future
The world around us changes rapidly, and prices for groceries and energy rarely stay the same for long. As jobs evolve and living expenses rise, testing your household safety score will become an essential life habit. Knowing your personal ratio gives you quiet strength, helping you face tomorrow with steady confidence no matter what happens in the wider economy.