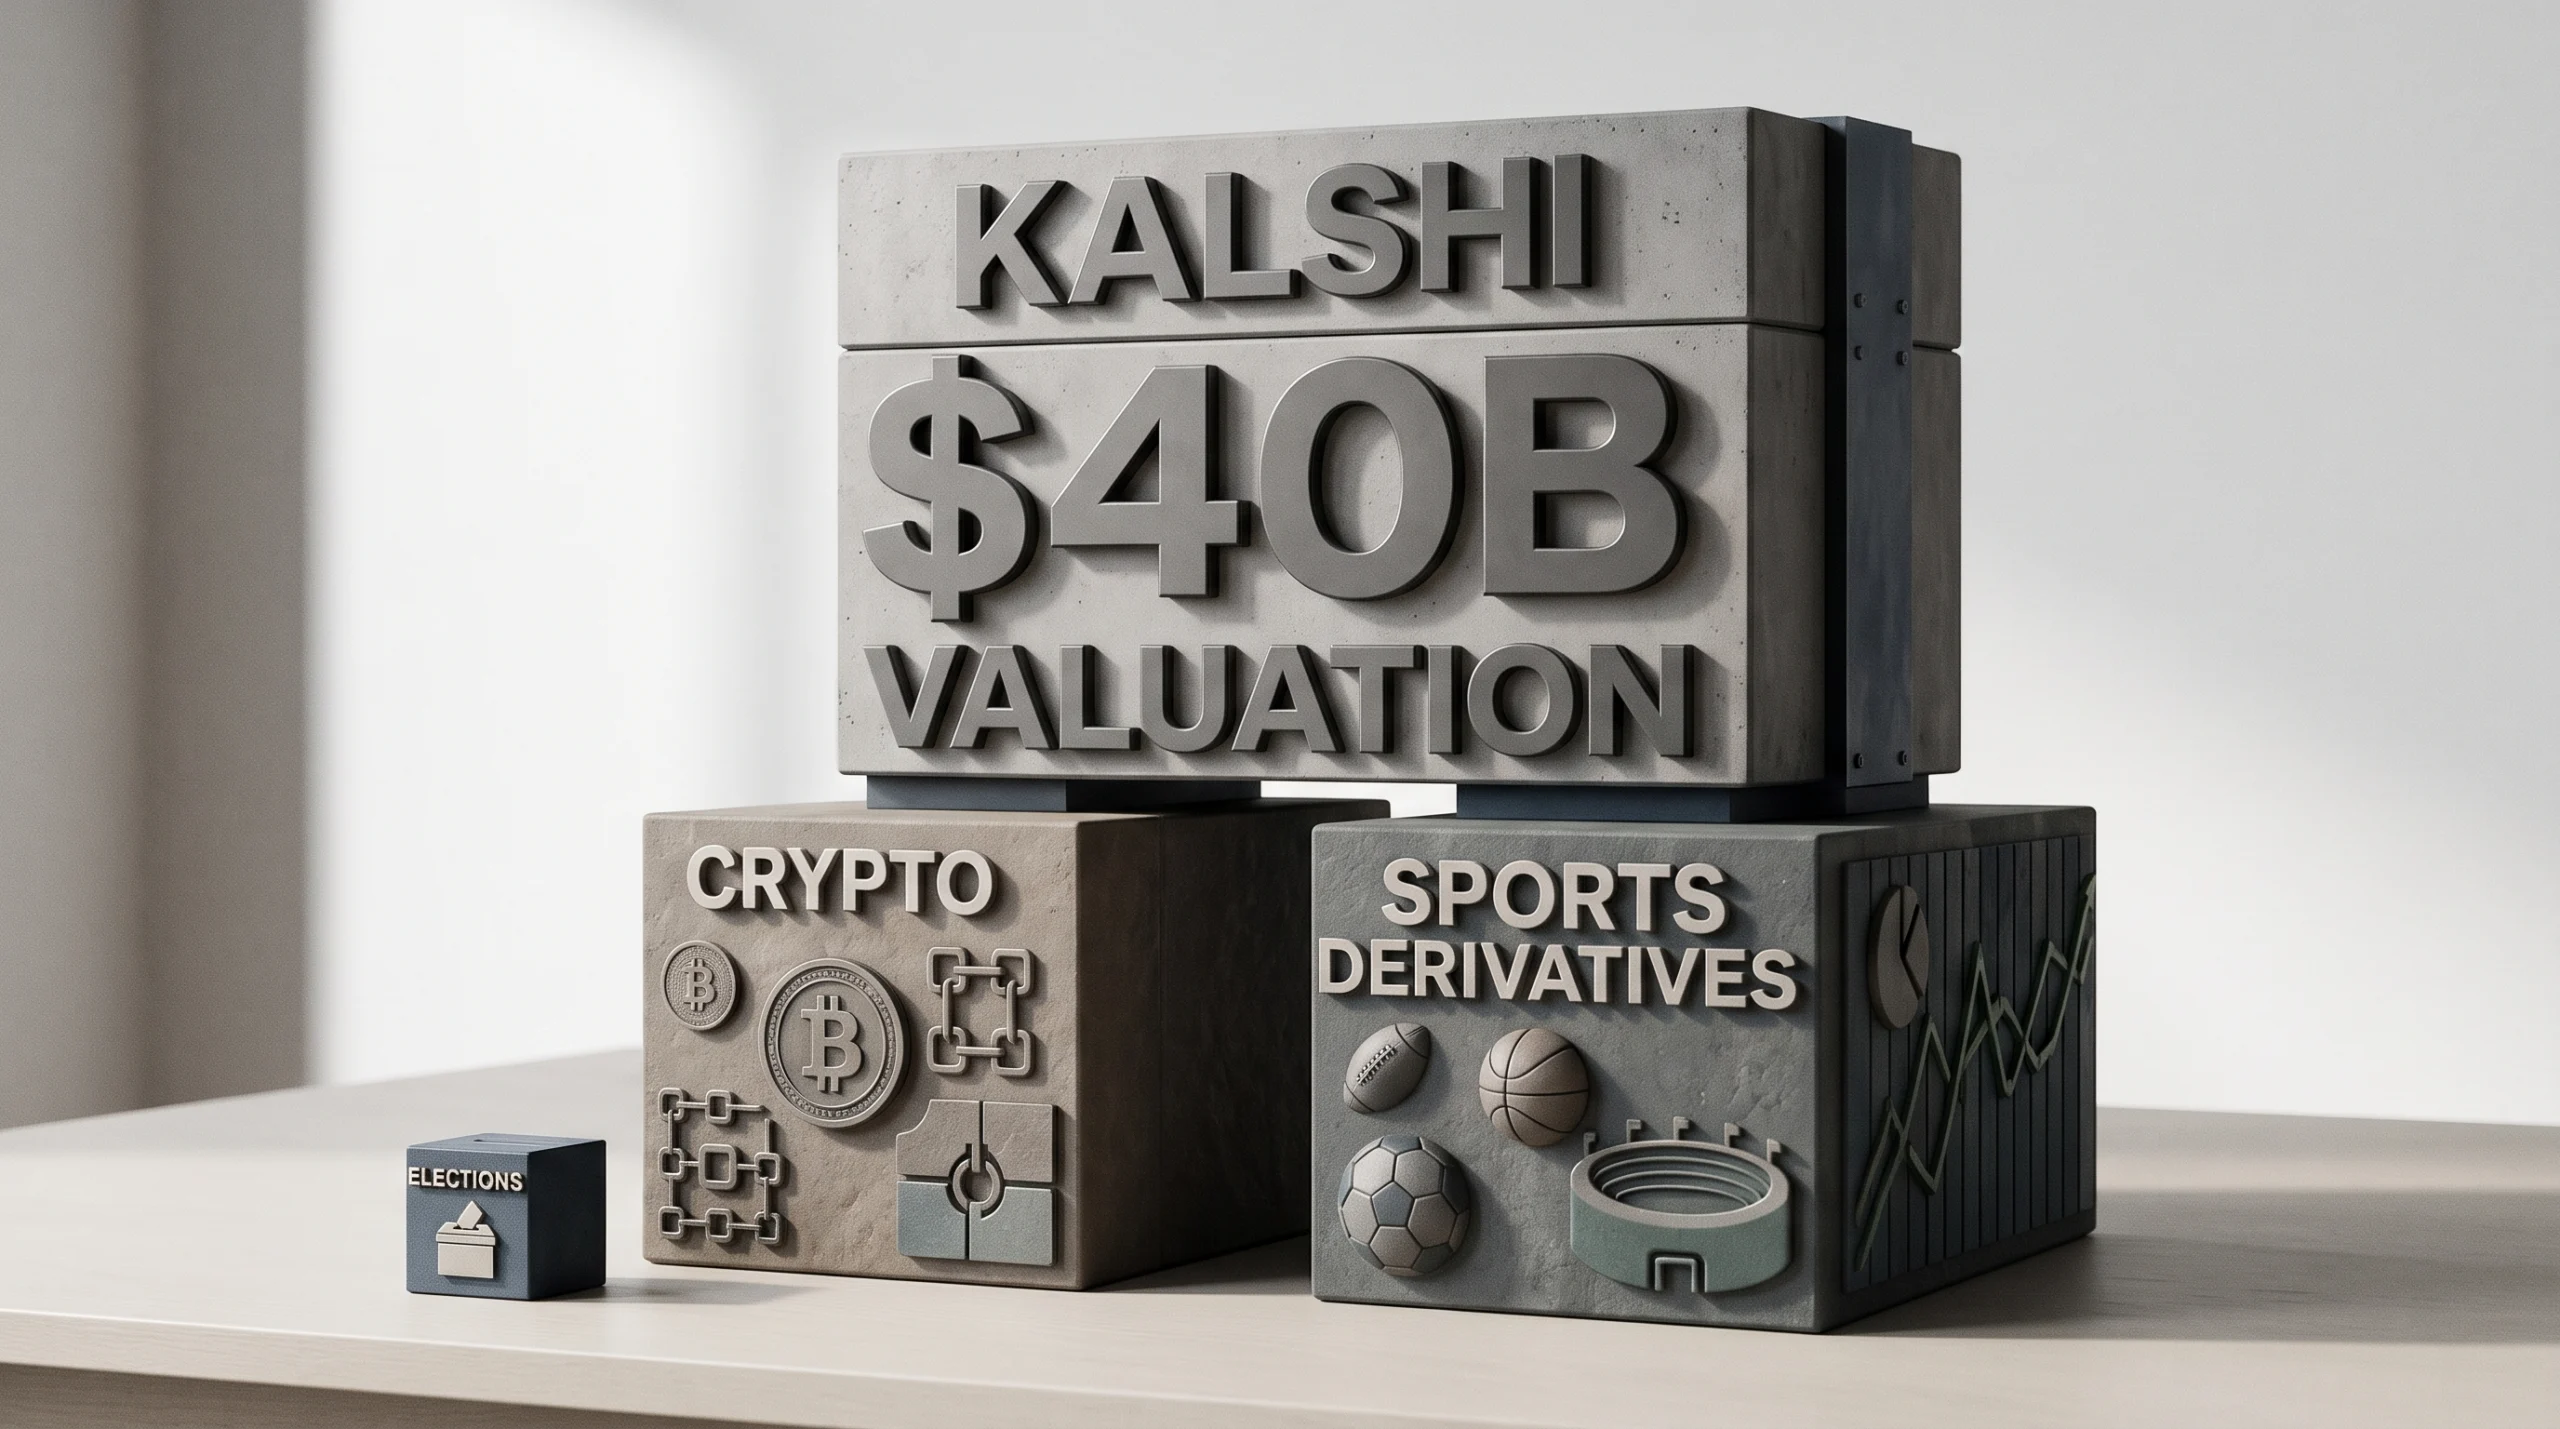
Regulated event contract exchange Kalshi secured one billion dollars in fresh venture financing at a remarkable forty billion dollar post money valuation. Popular media reports attributed this massive valuation milestone almost exclusively to public excitement surrounding upcoming midterm election betting. However, trading records show that political prediction contracts represent only a small fraction of the platform total turnover, with sports markets and perpetual derivatives driving true commercial expansion (from bloomberg.com).
Beyond Election Betting to High Volume Derivatives
While election forecasts capture public attention, Kalshi annualized transaction volume exceeded one trillion dollars primarily through financial hedging and athletic wagering contracts. Crypto asset contracts generated more than one hundred forty billion dollars in volume, accompanied by eighty billion dollars in perpetual futures trading. A perpetual future is a financial derivative contract that allows traders to speculate on an asset price without any designated expiration date. By combining high frequency sports outcome contracts with continuous synthetic crypto trading, the platform unlocked daily volume streams that rival established financial exchanges.
Institutional Market Makers and Fee Structure
Unlike casual gaming platforms that operate house odds, Kalshi functions as a genuine peer to peer clearinghouse. Leading institutional quantitative trading firms, including Hudson River Trading and Balyasny Capital, actively provide two sided liquidity across thousands of distinct order books. Kalshi earns a modest one basis point transaction fee on non sports contracts, equal to one one hundredth of one percent. This ultra low fee model encourages automated institutional algorithmic market makers to continuously provide deep bid and ask quotes, ensuring rapid order execution for retail participants.
Federal Regulation Clashes with State Gaming Laws
Kalshi rapid expansion has triggered intense legal disputes between federal authorities and individual state governments. Kalshi operates under an exchange license granted by the Commodity Futures Trading Commission, claiming complete federal preemption over state jurisdiction. Several state attorneys general contend that sports event contracts constitute unauthorized sports gambling subject to local gaming prohibition. A petition filed by the State of New Jersey has reached the United States Supreme Court, posing a pivotal legal test that will determine whether federal financial charters supersede state gambling statutes.
The Convergence with Traditional Stock Exchanges
If federal regulatory protections withstand court challenges, event contract marketplaces could disrupt legacy derivatives exchanges like CME Group and Nasdaq. Kalshi has already submitted regulatory proposals to list perpetual equity index futures directly for everyday retail investors. Allowing around the clock perpetual trading on major stock indexes could fundamentally alter how retail capital manages overnight volatility. Keeping track of regulatory determinations helps active traders understand emerging legal distinctions between financial derivatives and wagering products.