Personal finance personality Suze Orman has sparked widespread debate across the financial planning community by advising retirees to keep three to five years of basic living expenses parked in liquid cash outside their formal retirement accounts. The prominent commentator emphasizes that both equities and traditional fixed income bonds can experience simultaneous downturns, leaving retirees vulnerable if they lack an immediate cash cushion. While standard media articles praise the psychological peace of mind offered by large savings balances, certified financial professionals point out critical mathematical flaws and inflationary cash drag that can compromise long term portfolio longevity (from cnbc.com).
The Cash Drag Paradox in Long Term Portfolios
Holding substantial cash balances provides immediate emotional relief during turbulent market headlines, yet it introduces a persistent mathematical penalty known as cash drag. Cash drag occurs when holding non productive or low yielding currency reduces the overall compound investment return of an investment portfolio over extended periods. Rigorous financial research conducted by retirement experts William Bengen and Michael Kitces demonstrates that allocating fifteen to twenty five percent of total wealth into cash actually increases the mathematical probability of exhausting capital over a thirty year period. Because idle cash balances steadily lose purchasing power to persistent consumer price inflation, the remaining investment portfolio must generate unrealistically high returns to keep pace with rising living expenses.
The Missing Execution Rules for Tapping and Refilling Cash Reserves
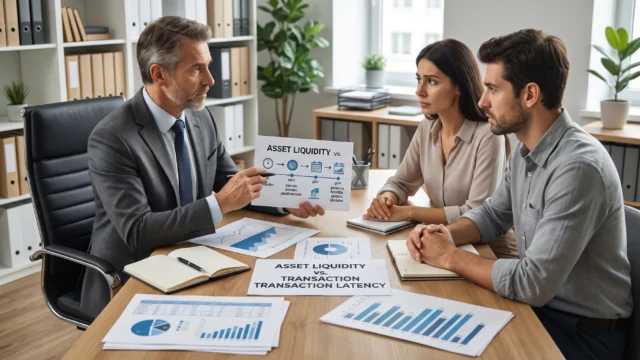
Advising retirees to maintain a multi year cash cushion sounds intuitive, yet practical implementation requires clear quantitative rules that define when to spend cash and when to rebuild reserves. Without predetermined market triggers, nervous retirees struggle to determine whether a ten percent correction or a twenty percent bear market justifies drawing from cash reserves rather than selling equity shares. Furthermore, standard advice rarely explains how to rebuild depleted cash reserves once the market begins to recover. In the absence of disciplined portfolio rebalancing guidelines, individuals frequently succumb to emotional panic, holding onto cash at market bottoms and failing to reinvest capital during early economic recoveries.
Reinvestment Risk and Changing Central Bank Policy
Retirees who accumulated multi year cash cushions during periods of elevated central bank interest rates face substantial reinvestment risks when monetary policy shifts. High yield savings accounts and short term certificates of deposit offer attractive yields when central banks maintain restrictive monetary policy, but those yields decline rapidly when interest rates fall. An individual who locks their multi year emergency reserves into floating rate bank accounts faces sudden reductions in annual interest income whenever economic conditions cool. Financial planners prefer constructing a bond ladder, which involves purchasing fixed income securities with staggered maturity dates across multiple years, to secure predictable guaranteed yields that shield household budgets from central bank rate cuts.
Comparing the Orman Rule with the Three Bucket Strategy
Retirees seeking balanced safety often implement the classic three bucket strategy as an alternative to maintaining an oversized static cash balance. Under the bucket framework, the first bucket holds one to two years of immediate cash expenses, the second bucket holds intermediate high quality bonds and short term government treasuries, and the third bucket remains invested in diversified global equities. This segmented structure provides ample liquidity to weather multi year market drawdowns without sacrificing the long term growth potential essential to offset inflation. Retirees should also avoid holding excessive cash reserves inside tax deferred retirement accounts, where conservative interest earnings fail to exploit valuable tax deduction opportunities.
Automating Cash Management in Modern Retirement
The evolution of modern financial technology is replacing static savings accounts with automated treasury management systems that optimize yield in real time. Rather than relying on rigid rules of thumb, modern wealth platforms dynamically allocate liquid reserves into inflation protected government securities and high quality short term paper. Establishing a disciplined liquidity strategy ensures that retirees enjoy genuine peace of mind during stock market declines while allowing their core investment capital to compound uninterrupted over decades of retirement.