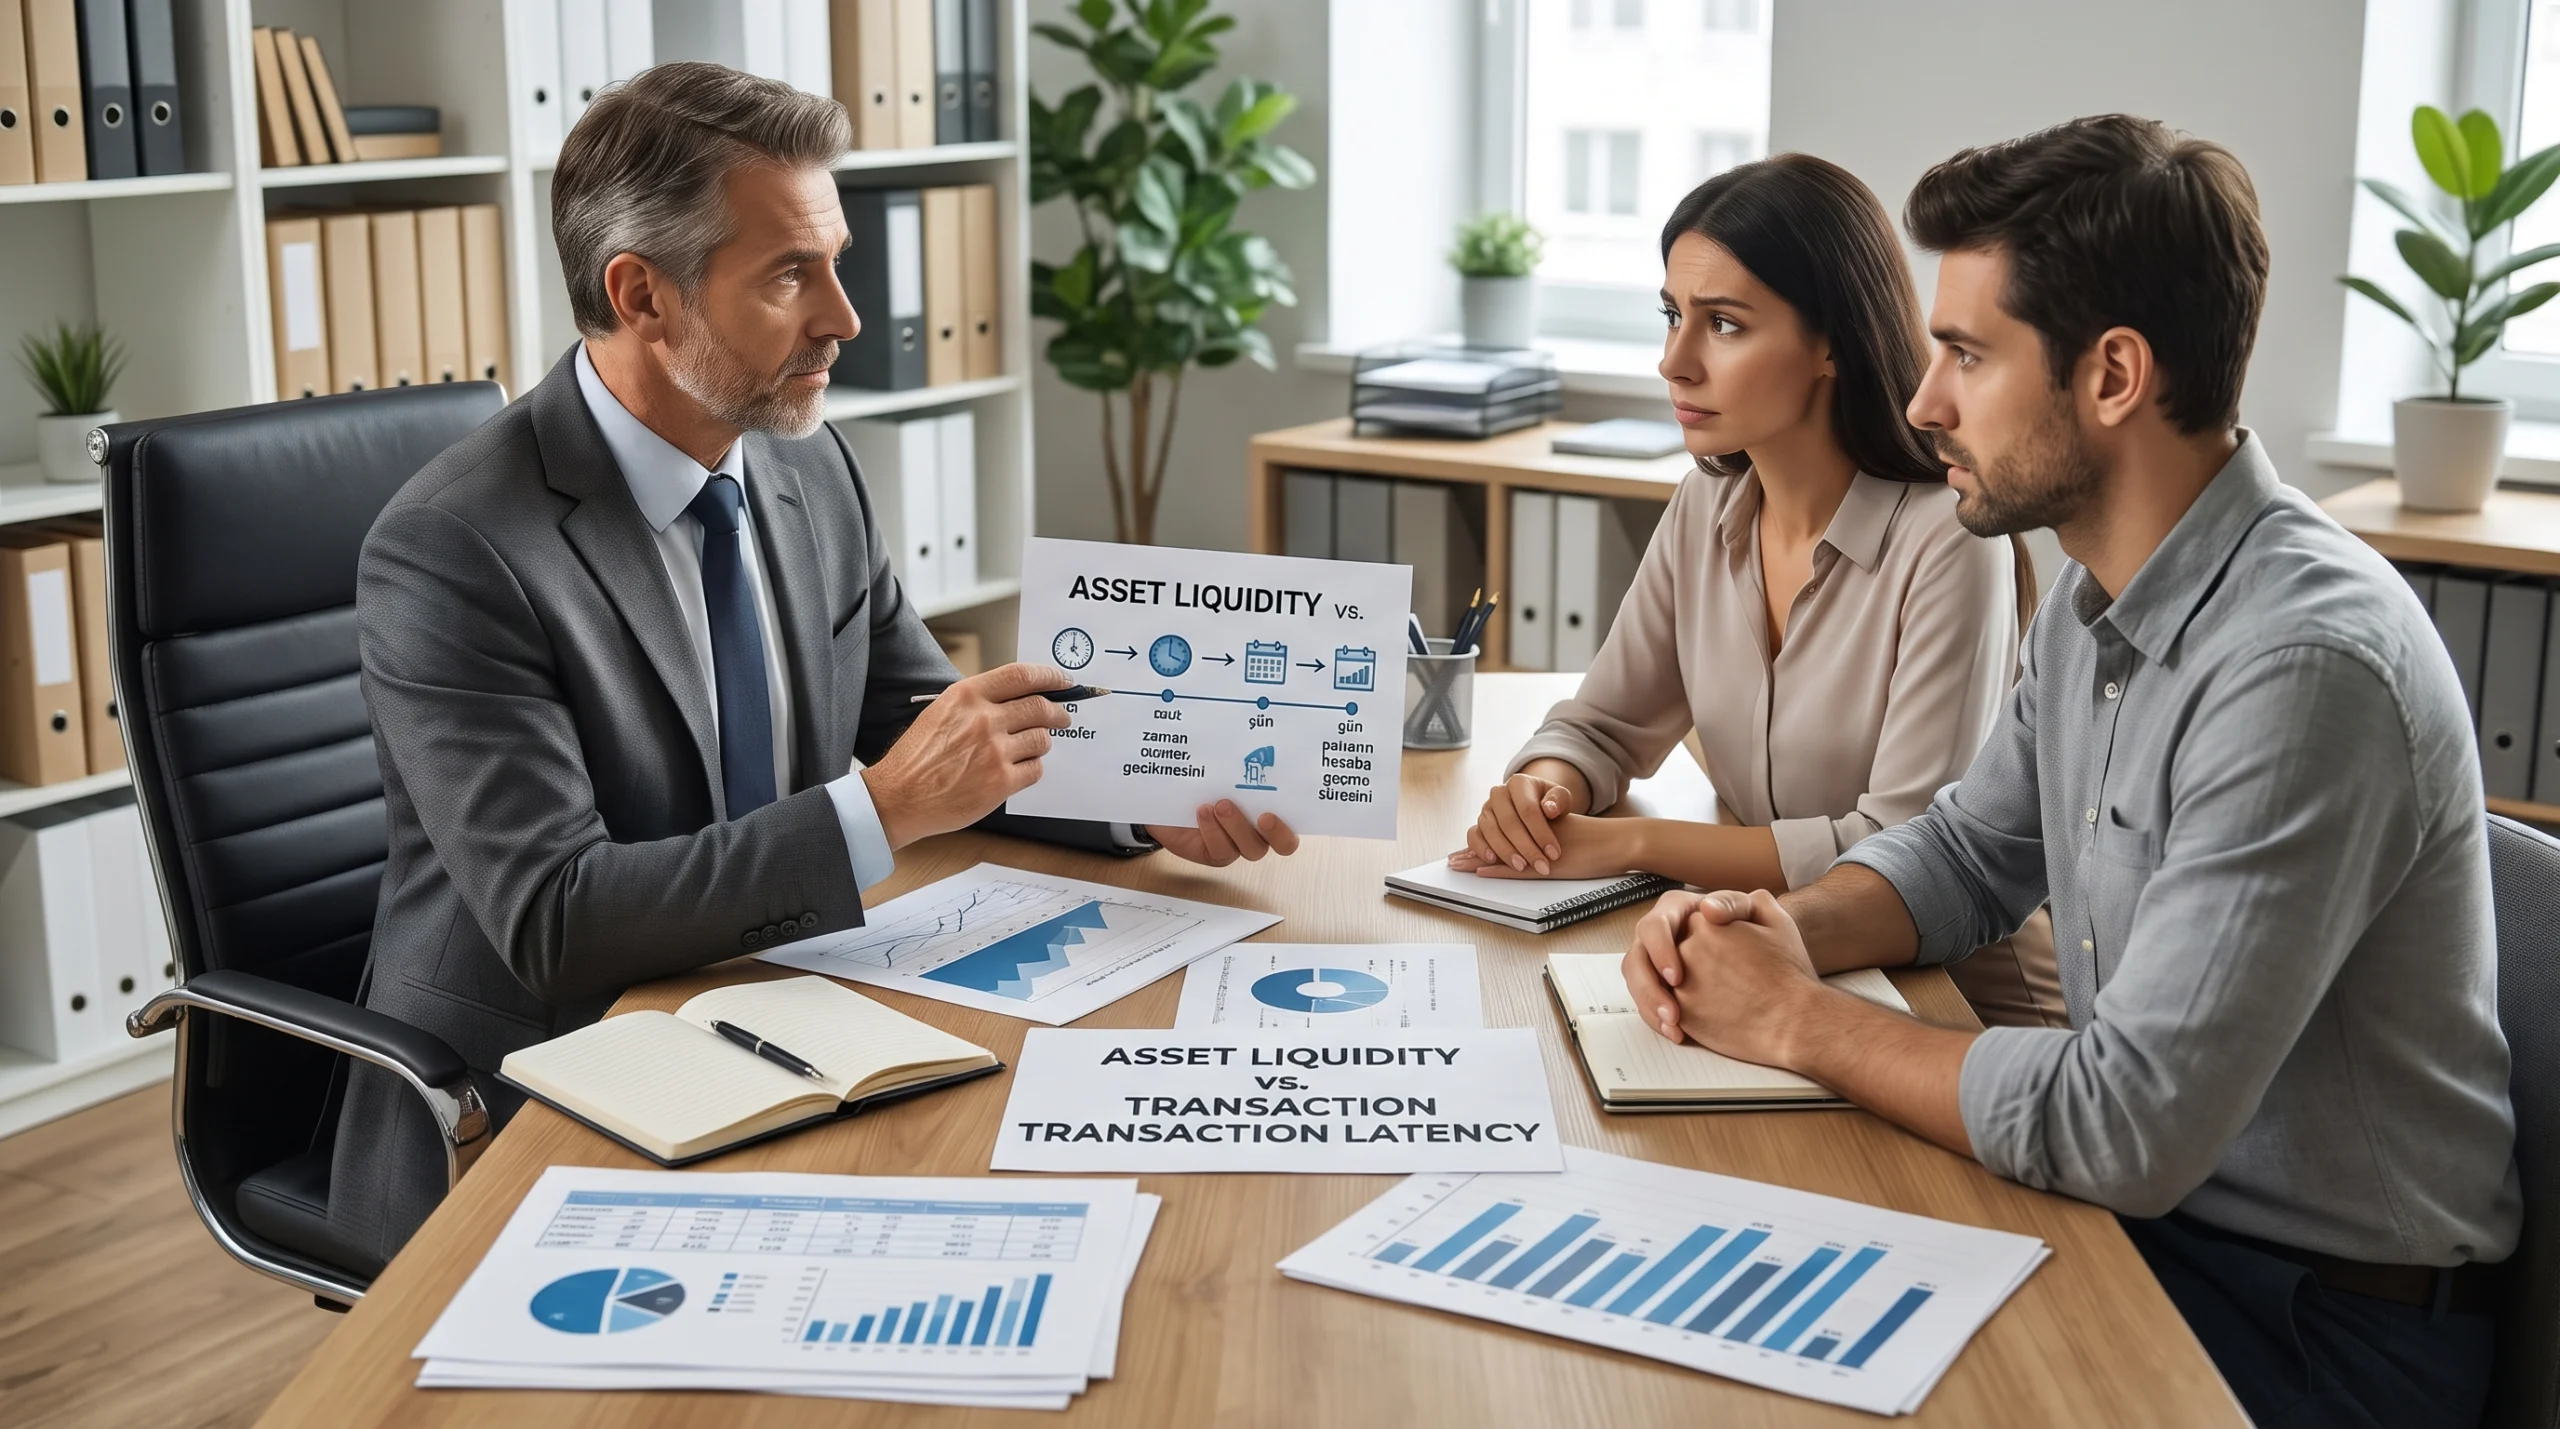
Personal finance discussions routinely emphasize the importance of maintaining adequate portfolio liquidity to survive economic emergencies. However, financial planners and everyday consumers frequently confuse asset liquidity with transaction latency. Asset liquidity measures the ability to convert an investment into currency without accepting a substantial loss in market value. In contrast, money latency measures the exact chronological time required for that value to become spendable cash at a physical retail checkout or against a credit card bill. Understanding the hidden technical bottlenecks in modern banking networks is vital to ensure funds arrive before urgent payment deadlines pass).
Asymmetric Clearance Delays in Electronic Bank Transfers
Most consumers assume that transferring capital between separate domestic bank accounts takes an identical amount of time regardless of how the transfer is initiated. In modern retail banking, initiating an electronic transfer from the receiving institution represents an automated clearing house pull request. Because pull requests carry elevated risks of unauthorized account takeover, receiving banks impose mandatory fraud risk holds that delay funds availability for three to five business days. Conversely, initiating the transaction from the sending bank represents an automated clearing house push transfer, which clearing networks process within twenty four hours. Initiating fund transfers from the sending institution significantly shortens the clearance window and avoids administrative account freezes.
The Calendar Friction in Modern Trade Settlements
Financial securities markets in North America recently adopted an accelerated one day settlement rule designed to reduce systemic credit risks across Wall Street brokerage houses. While an investor can execute the sale of an exchange traded index fund within seconds during regular market hours, accessing that cash in a local checking account involves substantial calendar friction. If an investor liquidates shares late on a Thursday afternoon, trade settlement concludes on Friday. However, the subsequent electronic wire transfer to an external commercial checking account encounters Friday afternoon cutoff deadlines. Consequently, the capital remains inaccessible throughout the weekend, delaying final spending availability until the following Tuesday morning.
Automated Fraud Alarms on Inactive Emergency Reserves
One of the most dangerous surprises during a personal financial crisis occurs when automated banking security algorithms freeze an emergency savings account. Individuals frequently leave substantial emergency cash reserves untouched inside high yield online savings banks for years at a time. When an unexpected crisis requires an immediate payment of fifteen thousand dollars, the sudden large transaction triggers automated velocity fraud tripwires. Banking security systems automatically lock the account to prevent identity theft, demanding manual identity verification that can take up to seventy two hours to resolve. Maintaining active checking accounts with established transaction histories helps prevent sudden security freezes during genuine family emergencies.
Constructing a Personal Capital Latency Ladder
Prudent financial management requires organizing household assets along a structured latency timeline that bridges immediate cash demands with higher yielding investments. Physical currency and credit card spending lines provide zero latency access to goods and services, functioning as an effective bridge while larger investment transfers clear. High yield checking accounts and short term treasury bills provide liquidity within one to two business days. Conversely, home equity lines of credit and hardship withdrawals from employer sponsored retirement plans can take more than three weeks to process. Utilizing a zero balance credit card as an interim liquidity bridge allows households to cover unexpected bills immediately while earning yield on conservative savings.
The Evolution of Instant Global Settlement Infrastructure
The implementation of modern instant payment rails like the federal FedNow system promises to eliminate traditional settlement delays across commercial banking networks. However, commercial banks intentionally maintain modest daily transfer caps on instantaneous payments to protect their core deposit bases from sudden liquidity drains. Over the coming decade, twenty four hour tokenized money market funds operating on distributed ledgers will gradually replace conventional fragmented interbank clearing networks. Until instantaneous wholesale settlement becomes universal, understanding money latency remains essential to safeguarding household financial stability.